Just the facts
Set a realistic budget.
Keep paperwork in one place.
Financing a new home build requires you to keep track of a lot of paperwork. Make sure to keep it all in one place that’s easy to access.
Prepare to get personal.
The loan process requires a lot of digging into your personal finances, income and employment history. Be prepared to share to get the ideal loan for you.
Guide to financing your new home
As a family-run business, Leogem Property Projects is all about bringing your home-ownership aspirations to life, in the most cost-effective and streamlined way possible. ??
We’ve curated a step-by-step guide that will enable you to seamlessly navigate the home financing process from pre-qualification to closing.?
01. Be realistic when determining your budget
Bond Calculator
Let’s establish your monthly bond re-payments with respect to the loan amount, loan term, interest rate and other factors. This feature determines how much you’ll be able to borrow by factoring in the purchase price, property and the Principal/Interest amount paid towards your investment
Rent vs. Own Calculator
We settle the 'rent vs buy' debate with a sliding scale that gives you a breakdown as to what would be more beneficial for your wallet.
Advice from the experts
The more accurate information you plug into the calculators the more accurate the results of your calculation will be. There’s no such thing as too much data!
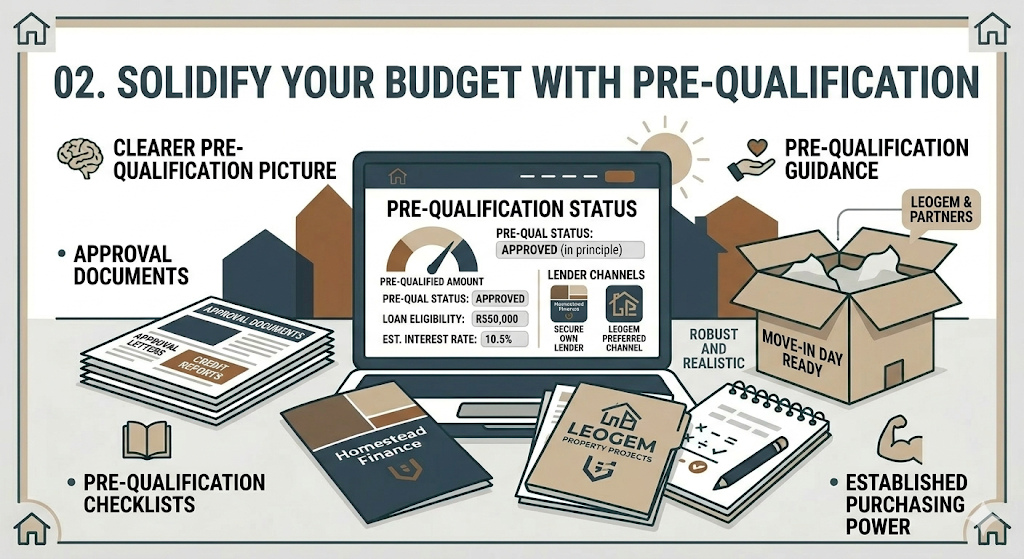
02. Solidify your budget with pre-qualification
Pre-qualifying is another way to ensure that your budget projections are robust and realistic. You might choose to secure your own lender, or alternatively work within Leogem Property Projects preferred channels – who can guide you along every step of the pre-qualification journey.
Working with Leogem Property Project’s preferred channels will guarantee that you will be assisted from now right up until the moment you close the deal. This benchmark should be adhered to irrespective of who you elect to be your lending partner throughout the process. ?
We provide a pre-qualification form online that enables you to get a head start on the process by profiling your purchasing power through a series of basic questions around your current living situation and finances.
At this point, your lender should revert back with a full credit history and profile, which will enable you to review and select the best loan option for you. If you choose to work with our lender, they’ll be in touch within 24 hours to help you determine your next steps.?
03. Apply for the loan that is relevant to you and your needs
Now that you’ve pre-qualified and you’ve chosen your dream Leogem home, we can begin the loan application process. The process begins with the completion of the application form, where you will need to divulge a fair amount of personal and financial information.
If you’re applying for a loan with a co-borrower, you should be mindful of the fact that they’ll typically have to share the same level of personal and financial information as you.
Here’s an inside look at the type of information that will be required from you throughout the loan application process (see the full list here):
Residence history:
Your previous addresses for the last two years and, if you’re renting, your current landlord’s name, address and phone number.
Employment and banking history:
Include the names and addresses of all your employers over the last two years, dates of employment and bank statements/pay-slips for the last 3 months.
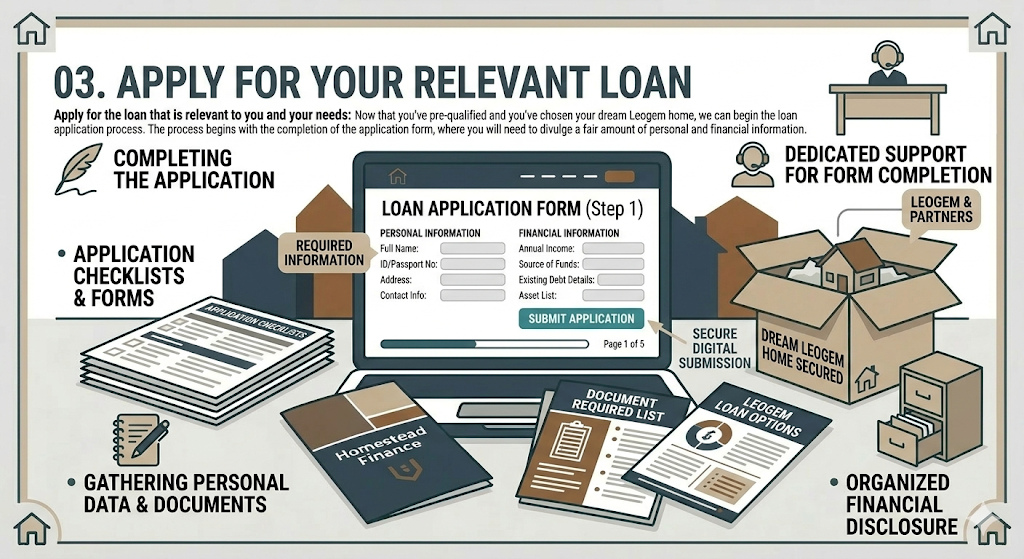
If you do it properly, you’ll do it once: The more detailed your personal and financial information, the better! Try and by as specific and comprehensive as possible – this will aid you in the long-run.?
04. Your loan processor is your teammate
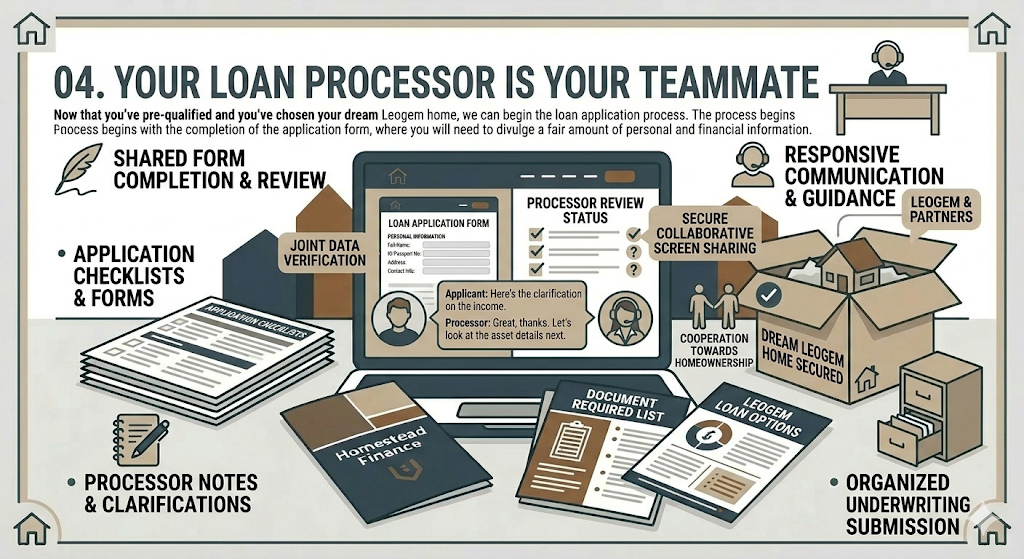
Now that you’ve pre-qualified and you’ve chosen your dream Leogem home, we can begin the loan application process. The process begins with the completion of the application form, where you will need to divulge a fair amount of personal and financial information.
If you’re applying for a loan with a co-borrower, you should be mindful of the fact that they’ll typically have to share the same level of personal and financial information as you.
Here’s an inside look at the type of information that will be required from you throughout the loan application process (see the full list here):
Residence history:
Your previous addresses for the last two years and, if you’re renting, your current landlord’s name, address and phone number.
Employment and banking history:
Include the names and addresses of all your employers over the last two years, dates of employment and bank statements/pay-slips for the last 3 months.
05. Follow up with the underwriter
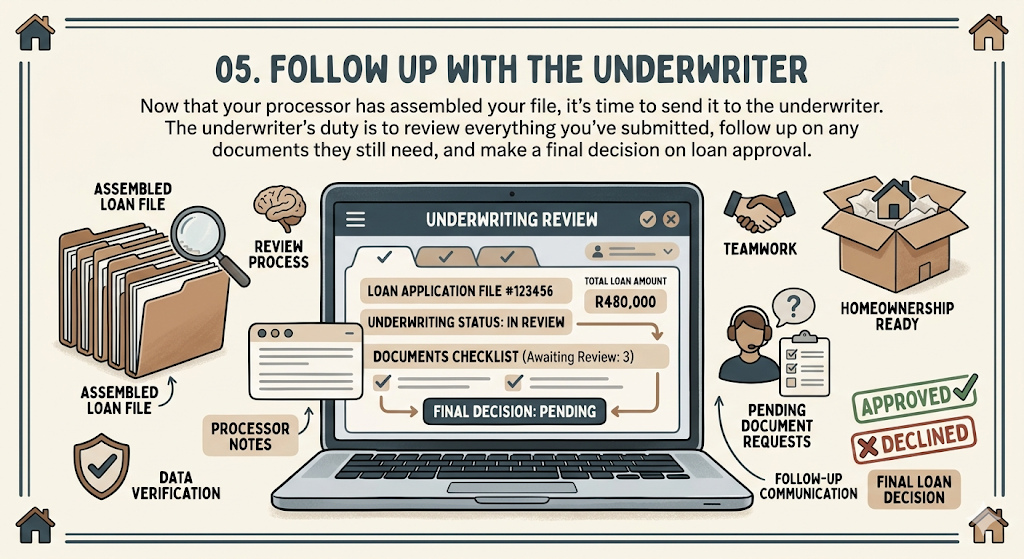
Your processes has assembled your file, now it’s time to send it on to the underwriter. The underwriter’s duty is to review everything you’ve submitted, follow-up on any documents they still need and make a final decision on loan-approval.
The decision is typically based on five factors:
- Income
- Assets
- Financial obligations
- Credit report
- Property value
06. Get your interest rate locked-in
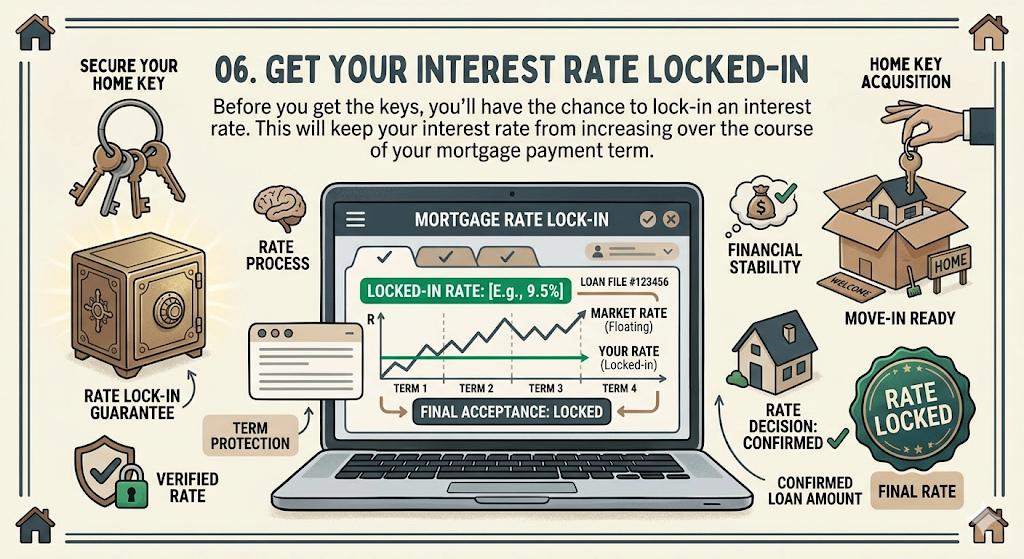
Before you get the keys, you’ll have the chance to lock-in an interest rate. This will keep your interest rate from increasing over the course of your mortgage payment term.
Advice from the experts:
Interest rates change often – what you lock-in today might not be the exact figure that you see closer to closing day.?
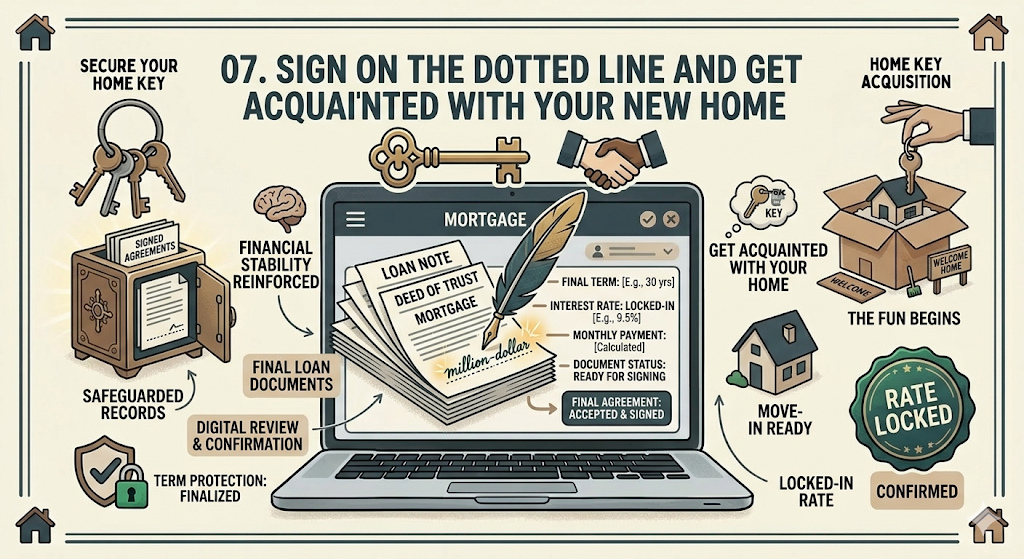
07. Sign on the dotted line and get acquainted with your new home
This is the where the fun begins. Your loan documents should be ready for your million-dollar signature. They’ll include the note, deed of trust or mortgage, and supporting disclosures.
Transfer of the property is the final step in this process. All the documents that make your homeownership official are signed and processed via the appointed attorneys and conveyancers.
Here’s a quick ‘closing’ guide to aid you in the process:
- Get homeowner’s insurance: One month before your move in date, choose an insurance provider. You’ll be asked to provide proof of your home insurance by the transfer date. Or you could go with the insurance provided by your bank.
- Provide the right documentation: Make sure to keep your tax returns and financial records accessible during your move. Because loans are subject to multiple reviews and final conditions can be added at any time, you could be required to produce additional information or documentation.
- Invite every borrower to the closing: each person listed as a borrower or co-borrower needs to sign the transfer documents. If a signer can’t make it to the closing appointment, make arrangements beforehand with your mortgage company and the transferring attorney.Once every document has been executed and recorded and we have received the confirmation of transfer, you’ll officially be a part of the Leogem family and we will personally give you the keys to your brand new home.