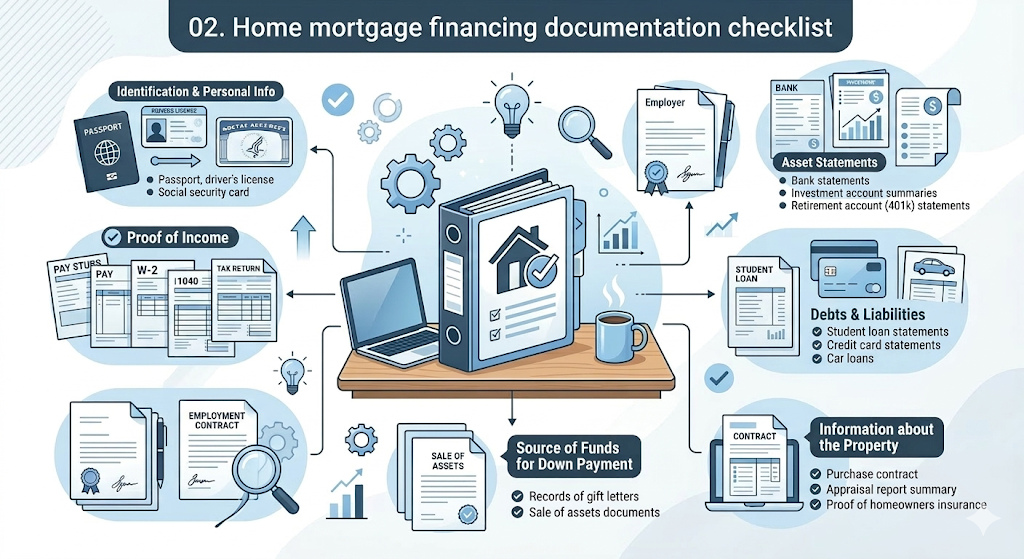
Chapter Two: Home mortgage financing documentation checklist
Home mortgage financing documentation checklist
Your home mortgage financing documentation checklist.
When it comes to applying for a home mortgage loan, you’ll be asked to collect and share what may feel like a significant amount of your personal information. This is to be expected, and in being thorough, you can actually help make the process even more seamless. Take a look at some of what you’ll be asked to share
Personal documentation
Residence history
In addition to looking at your Driver’s license number and ID number, most lenders will also cross-reference your address to verify your identity and any existing home loans.
Your lender typically will review:
- Previous addresses for the last two years
- Your current landlord’s name, address and phone number (if applicable)
Employment history
Because employment is a major factor in qualifying for a home loan, lenders pay close attention to how long someone has been employed. Specifically, they look at the duration of employment, as this indicates financial stability. It’s also important to note that some lenders may call your previous place of employment to verify the information you provided.
They’ll typically review:
- Names and addresses of all employers for the last two years, and dates of employment with each
- Payroll —or other proof of income—for the last 30 days
- Two years of SARS and IRP5
- Year-to-date profit and loss statement and IT34 (if self-employed)
Financial history
One of the most important aspects of applying for a home loan is providing insights into your financial history. Your lender will review your chequing accounts, savings accounts, and any other financial or banking account information provided. This will ultimately help them determine how much you can afford to borrow, plus what you will need to have saved for a deposit payment and any closing costs.
At this point, they’ll typically review:
- Last three months’ worth of bank statements from your savings and cheque accounts
- Recent statements from any investment and retirement accounts
- Proof of earnest-money, such as: contracting, deposits, etc
- Proof of closing funds
- Other existing loans, such as personal or student loans
- Copy of your most recent property municipal account (if you currently own a home)
- Copy of your most recent homeowner’s insurance bill (if you currently own a home)
- Copy of your most recent mortgage statement (if you currently own a home)
Additional documentation
In addition to the above documents, which are standard across almost all lenders today, you may be asked to provide additional documentation that explains special, unique or uncommon circumstances.
Your lender will specify what documents are needed, but they may include any of the following (if applicable):
- Complete rehabilitation papers, including discharge if bad debit was incurred
- Complete divorce papers in divorced instances
- Signed and dated letters that explain certain situations, such as switching from full-time employment to self-employment
- Verification of child support or alimony payments
Having these documents prepared in advance can save you a lot of time and trouble. It will also make the entire loan process smoother and faster, preventing unwanted delays.
For a more in-depth look at your own personal new home build financing process, call our offices to chat with our finance liaison to feel prepared and confident at every step.